The Seller Has a Mortgage Rate You Can Only Dream Of. Could You Take It Over?
The Seller Has a Mortgage Rate You Can Only Dream Of. Could You Take It Over?
Imagine finding a home in Houston that checks nearly every box. The location works, the layout fits your lifestyle, and the price is within reach. Then you discover something unexpected: the seller has a mortgage with an interest rate far below what you might qualify for today.
What if you could take over that mortgage instead of getting a completely new one?
It may sound too good to be true, but in some cases, it is possible. The strategy is called an assumable mortgage, and it could give eligible buyers an opportunity to take advantage of an existing loan's interest rate and terms.
However, there's a catch. Not every mortgage qualifies, and taking over a seller's low rate doesn't necessarily mean you can afford the home more easily.
Before you start searching for homes with unusually attractive mortgage rates, here's what Houston buyers need to understand.
What Is an Assumable Mortgage?
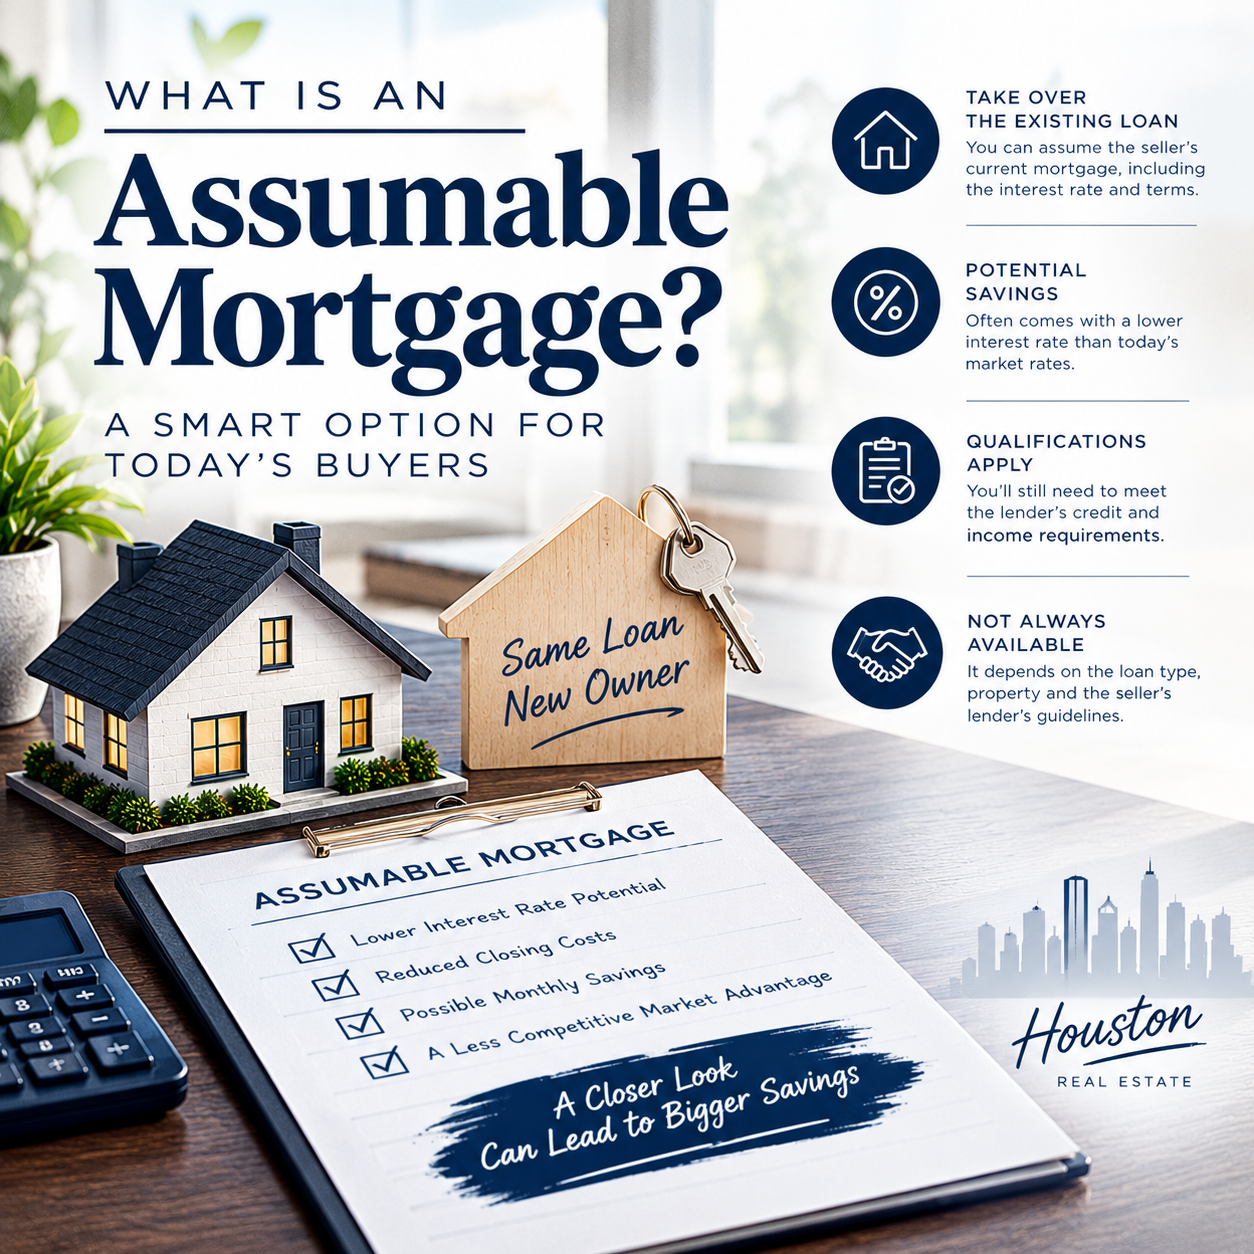
An assumable mortgage allows a qualified buyer to take over a seller's existing home loan, including its remaining balance, interest rate and repayment terms, subject to lender approval.
Instead of obtaining an entirely new mortgage, you assume responsibility for the existing loan.
For example, imagine a seller has a mortgage with a 3% interest rate and still owes $250,000. If the loan qualifies for assumption and the lender approves you, you may be able to take over that remaining balance at the existing rate.
That could be appealing compared with financing the same amount at a higher interest rate.
But the loan balance is only part of the purchase price. If the home is worth considerably more than the amount remaining on the mortgage, you'll need a plan to cover the difference.
The low interest rate may attract your attention, but the total cost of buying the home should determine whether the opportunity makes sense.
Which Mortgages Can You Actually Take Over?
Here's where buyers need to be careful: most mortgages cannot simply be transferred to another buyer.
Government-backed loans, including many FHA, VA and USDA mortgages, are generally assumable, subject to the applicable programme requirements and lender approval. Most conventional mortgages are not assumable in an ordinary home sale.
That means you cannot assume a seller has an assumable loan just because they advertise a low interest rate.
Before making an offer, ask whether the existing mortgage is eligible for assumption and contact the loan servicer to understand the requirements.
A seller's willingness to let you take over the payments is not enough. The transfer must follow the loan's terms and be properly approved.
The Biggest Catch: You May Need More Cash Up Front
Let's say you find a Houston home priced at $400,000. The seller has an assumable mortgage with a remaining balance of $260,000.
The difference is $140,000.
That gap represents the portion of the purchase price not covered by the existing mortgage. You would need to cover it through available cash, acceptable additional financing or another arrangement permitted by the lenders involved.
This is where an attractive mortgage rate can become more complicated.
Even if the existing loan offers a lower monthly principal-and-interest payment, you may need substantial funds to complete the purchase. A second loan could also introduce a separate interest rate, payment and approval process.
Before pursuing an assumable mortgage, calculate the full amount you'll need at closing, not just the payment attached to the seller's loan.
Could Taking Over a Low Mortgage Rate Save You Money?
Potentially, yes. The benefit depends on the existing loan balance, interest rate, remaining term, your financing needs and the total cost of purchasing the property.
Consider a simplified example: two buyers are financing the same $250,000 balance over 25 years. One has a 3% interest rate, while the other has a 6.5% rate.
The estimated monthly principal-and-interest payments would be approximately $1,185 and $1,688, respectively.
That's a difference of about $503 per month, before property taxes, homeowners insurance, mortgage insurance, fees or other housing expenses.
This is an illustration, not a quote or a guarantee of savings. An actual assumption may involve a different remaining loan term, balance and upfront cost.
The important question is whether the potential payment savings outweigh the equity gap, fees and any additional financing you need.
What Buyers Should Know Before Making an Offer
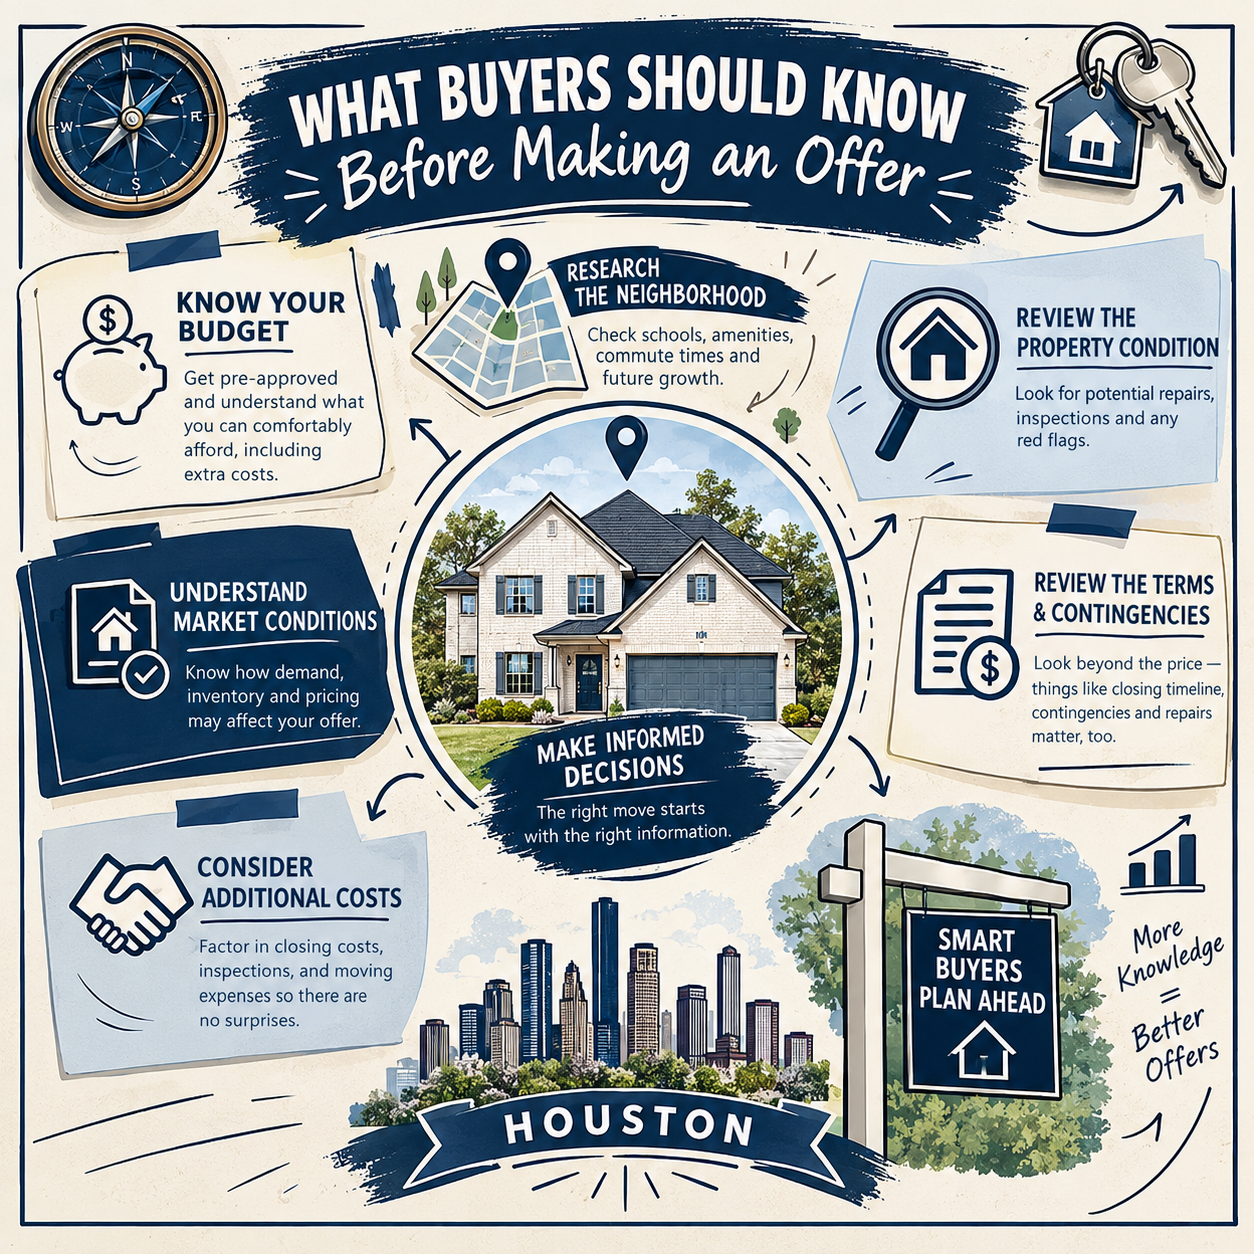
An assumable mortgage still requires a proper process. Buyers generally need to submit financial information and meet the loan servicer's eligibility requirements. The process can also take longer than a conventional home purchase, depending on the lender and the circumstances.
Before moving forward, confirm the loan type, outstanding balance, interest rate and remaining term. Ask the servicer about qualification requirements, assumption fees, expected timing and whether the seller will be formally released from liability.
You should also compare the total monthly housing cost, including property taxes, insurance, HOA fees and any mortgage insurance that applies.
A lower interest rate is valuable only when the complete financing arrangement fits your budget.
What About Sellers With Low Mortgage Rates?
Assumable mortgages may also create an opportunity for homeowners who locked in a low rate several years ago.
If your mortgage qualifies, the possibility of assumption could make your property more appealing to certain buyers. It may help distinguish your listing from competing homes, particularly for buyers who are concerned about financing costs.
However, an assumable loan does not guarantee a faster sale or a higher price. Buyers still need to qualify, cover any equity difference and be comfortable with the property's total cost.
Sellers should work with their loan servicer and real estate professional to verify the assumption terms before advertising the feature. For homeowners with VA loans, there may also be implications for their VA loan entitlement if the buyer does not meet the applicable substitution requirements.
Is an Assumable Mortgage Right for You?
For some buyers, assuming an existing mortgage could offer meaningful savings. For others, the equity gap, additional financing needs or lengthy approval process may make a traditional mortgage more practical.
The best starting point is to compare both options using real numbers. Look beyond the advertised rate and consider the total cash needed, monthly housing expenses, loan terms and your plans for the property.
For sellers, understanding whether your existing mortgage is assumable could be another way to position your home in a competitive market.
Find the Right Homebuying Strategy in Houston
A low mortgage rate can make a home worth a closer look, but it shouldn't be the only reason you buy it. Understanding the property's value, the financing structure and the full cost of ownership can help you make a more confident decision.
The Gonzalez Legacy Group helps Houston-area buyers and sellers navigate changing market conditions and explore their real estate options.
If you're searching for a home or preparing to sell, connect with The Gonzalez Legacy Group to discuss your goals and develop a strategy that fits your next move.
Categories
Recent Posts
Team Lead, Trusted Real Estate Advisor License ID: 0542785
+1(832) 766-0195 | elisa@gonzalezlegacygroup.com