The Mortgage Payment Looks Affordable Today. What Happens When the Rate Changes?
The Mortgage Payment Looks Affordable Today. What Happens When the Rate Changes?
A home may fit your budget today, but will it still feel affordable a few years from now?
For Houston homebuyers, the monthly mortgage payment is often one of the first numbers they consider. A lower initial payment can make a property seem like the right choice, especially when buyers are balancing their down payment, closing costs and everyday expenses.
But there's one important question worth asking before signing: Will your mortgage payment stay the same, or could it increase later?
Understanding how your interest rate works can help you avoid surprises and choose a home that fits your finances beyond the first few months.
Why Your Mortgage Payment Could Change
Not every mortgage works the same way.
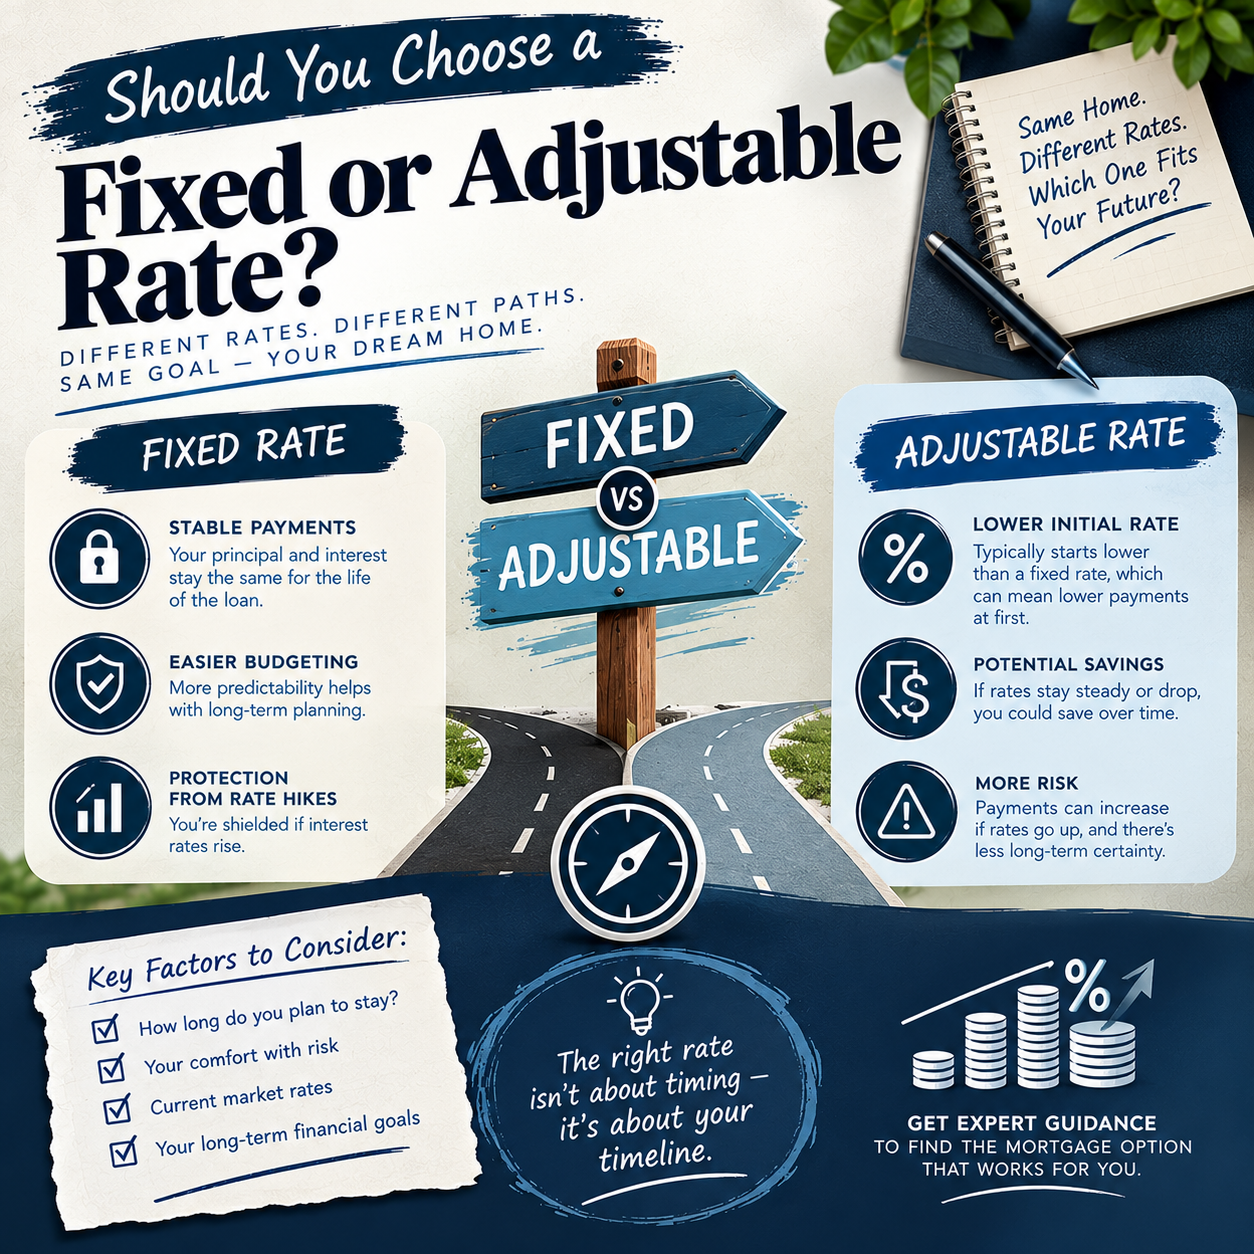
With a fixed-rate mortgage, your interest rate generally stays the same throughout the loan term. Your principal-and-interest payment remains stable, although property taxes, homeowners insurance and other housing expenses can change.
An adjustable-rate mortgage (ARM) works differently. It may begin with a lower introductory interest rate, but after the initial period, the rate can adjust based on market conditions and the terms of your loan. If the rate rises, your monthly principal-and-interest payment may rise as well.
According to the Consumer Financial Protection Bureau, buyers should understand how soon an ARM can adjust, how frequently changes occur and how high the payment could become.
The initial payment is only part of the picture. You also need to understand what comes next.
The Risk of Choosing a Home Based on Today's Payment
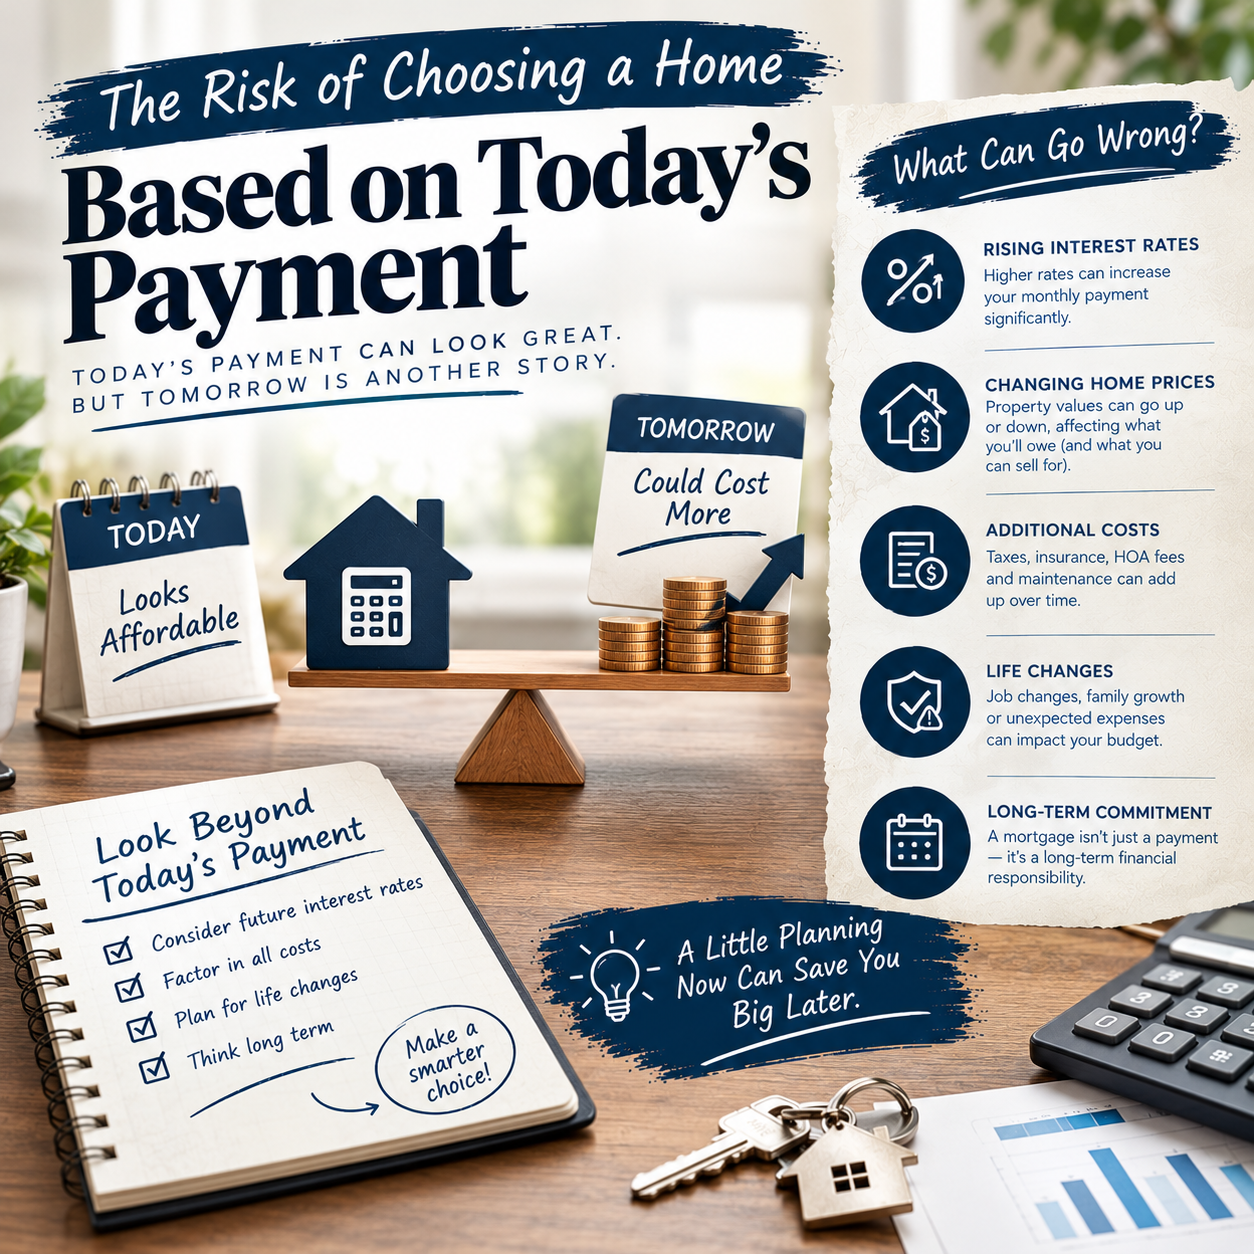
Imagine finding a home in the Greater Houston area that fits your current monthly budget. The payment looks manageable, and you feel comfortable moving forward.
But what happens if your adjustable rate increases after the introductory period?
A higher payment could leave less room in your budget for groceries, transportation, savings, repairs and unexpected expenses. If your household income changes at the same time, managing those costs could become even more difficult.
This doesn't mean an adjustable-rate mortgage is automatically the wrong choice. Depending on your financial circumstances and plans, it may be worth considering. The important thing is to understand the potential changes before deciding.
What Buyers Should Check Before Choosing a Mortgage
Before committing to a loan, ask your lender a few important questions.
When can the rate change? Find out how long the initial rate lasts and how often adjustments can occur afterward.
How much could the payment increase? Ask about the loan's initial, periodic and lifetime rate caps. These limits determine how much the interest rate can change under the loan agreement. They do not necessarily guarantee that the resulting payment will fit your budget.
What determines the new rate? For many ARMs, the future rate is based on an index plus a lender-set margin, subject to the loan's terms and applicable caps.
Could you still afford the home at a higher payment? Ask your lender to calculate the maximum possible payment under the loan terms. Build your budget around a realistic range rather than relying only on the initial payment.
You can also review the CFPB's guide to adjustable-rate mortgage terms before comparing loan options.
Don't Forget the Other Costs of Owning a Houston Home
Your interest rate isn't the only factor that affects affordability.
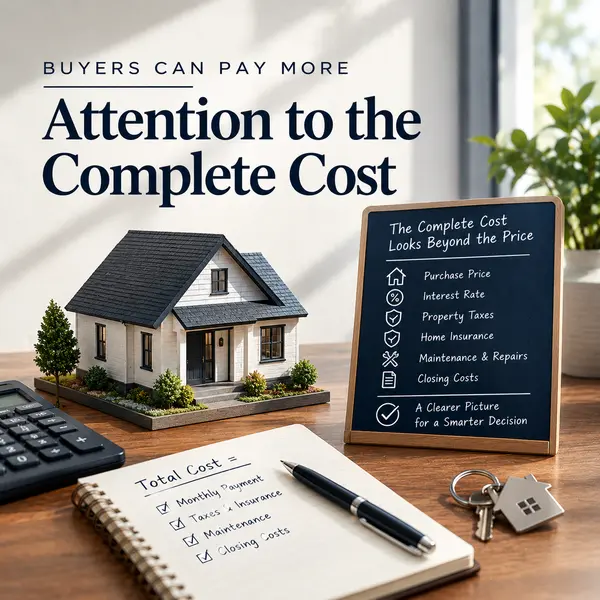
Property taxes, homeowners insurance, possible flood insurance, utilities and ongoing maintenance can all influence the true cost of owning a home. In some Houston-area communities, buyers may also need to investigate homeowners association fees or special district taxes.
These expenses can change even if you have a fixed-rate mortgage.
Before making an offer, look beyond the advertised payment. Review the property's tax information, obtain insurance estimates and consider the age and condition of the home. A payment that works on paper may feel very different once all the monthly expenses are included.
Should You Choose a Fixed or Adjustable Rate?
There is no single answer for every buyer.
A fixed-rate mortgage may appeal to buyers who value predictable principal-and-interest payments and expect to stay in their home for many years.
An adjustable-rate mortgage may suit some buyers who understand the risks, have sufficient financial flexibility and have a clear reason for choosing a loan with a changing rate.
However, don't assume you can simply sell the property or refinance before the rate increases. Your circumstances, home value and future lending conditions may be different when that time arrives.
The right decision depends on your finances, your plans and the specific terms of the loan, not just which option offers the lowest initial payment.
Buy a Home That Fits Your Future, Not Just Your Budget Today
Buying a home should be an exciting milestone, not a financial decision that leaves you worrying about the next rate adjustment.
Before you start touring properties, understand your complete monthly budget, discuss mortgage options with a qualified lender and consider how your finances might handle a higher payment. A little preparation can help you approach your home search with greater confidence.
At The Gonzalez Legacy Group, we help Greater Houston buyers navigate the home search, compare properties and make informed decisions based on their needs and goals. While your lender can explain financing options and payment scenarios, our team can help you evaluate the property itself and find a home that aligns with your priorities.
Ready to begin your Houston-area home search? Contact The Gonzalez Legacy Group to discuss your real estate goals and take your next step with confidence.
Categories
Recent Posts
Team Lead, Trusted Real Estate Advisor License ID: 0542785
+1(832) 766-0195 | elisa.gonzalez@exprealty.com